Read more information on the details of our price cap for high-cost short-term credit loans.
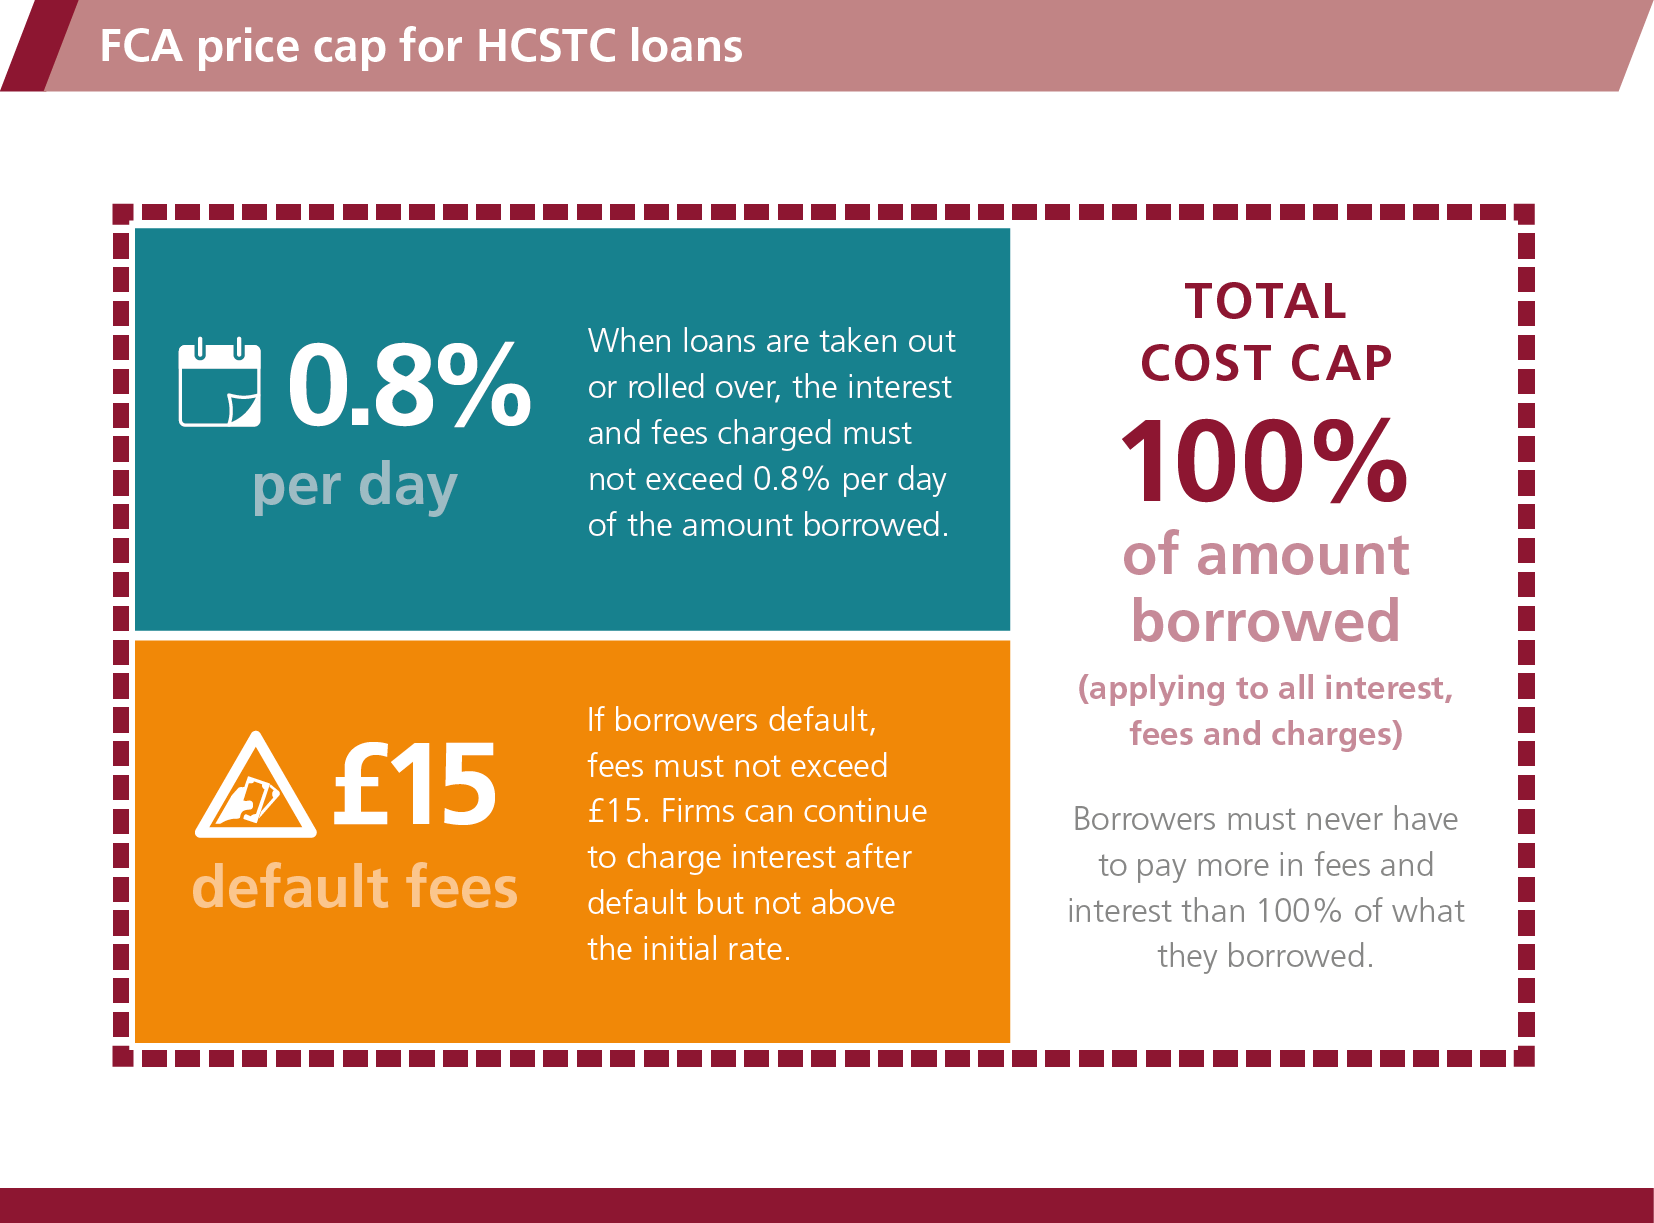
In December 2013, Parliament gave us a duty to introduce a price cap to protect consumers from excessive charges from high-cost short-term credit (HCSTC). The harm included rates that were then as high as 4% per day with a typical customer taking out 6 loans per year.
Our remedies: A price cap, risk warnings and restrictions
We introduced a price cap with effect from 2 January 2015. This followed the introduction of risk warnings to consumers and restrictions on rollovers and how recurring payments are collected.
2017 review
We reviewed our HCSTC rules in 2017. We found that our reforms had led to cheaper loans, better affordability assessments, and fewer customers experiencing debt problems with payday loans. Following that review, we decided to maintain the existing level of the cap.
2026 review
We recognise the role of HCSTC in supporting consumers' short-term financial needs. Having committed to reviewing the cap again, we engaged with industry and consumer stakeholders and assessed the feedback received.
There was broad support across the different stakeholders for keeping the price cap to ensure consumer protection and market stability. There was no strong call for its level to change, with stakeholders acknowledging the possible trade-offs with access to credit.
In September 2026, we decided not to proceed with the second stage of the review (the data analysis stage). We will instead use data, including the new consumer credit product sales data, to monitor the market in order to identify the circumstances in which further analysis or a review of the price cap may be needed in the future.